

How to open a US bank account without an SSN

If you’re wondering whether you can open a U.S. bank account without a Social Security number (SSN), the short answer is yes. Many banks and credit unions accept an Individual Taxpayer Identification Number (ITIN) in place of an SSN, and some will take a valid passport alone.
It’s one of several practical hurdles newcomers run into. Our post on the financial barriers many U.S. immigrants face covers a few of the others. This guide sticks to the bank account itself.
What you need to open a bank account without an SSN
The exact list varies by bank, but you’ll generally need:
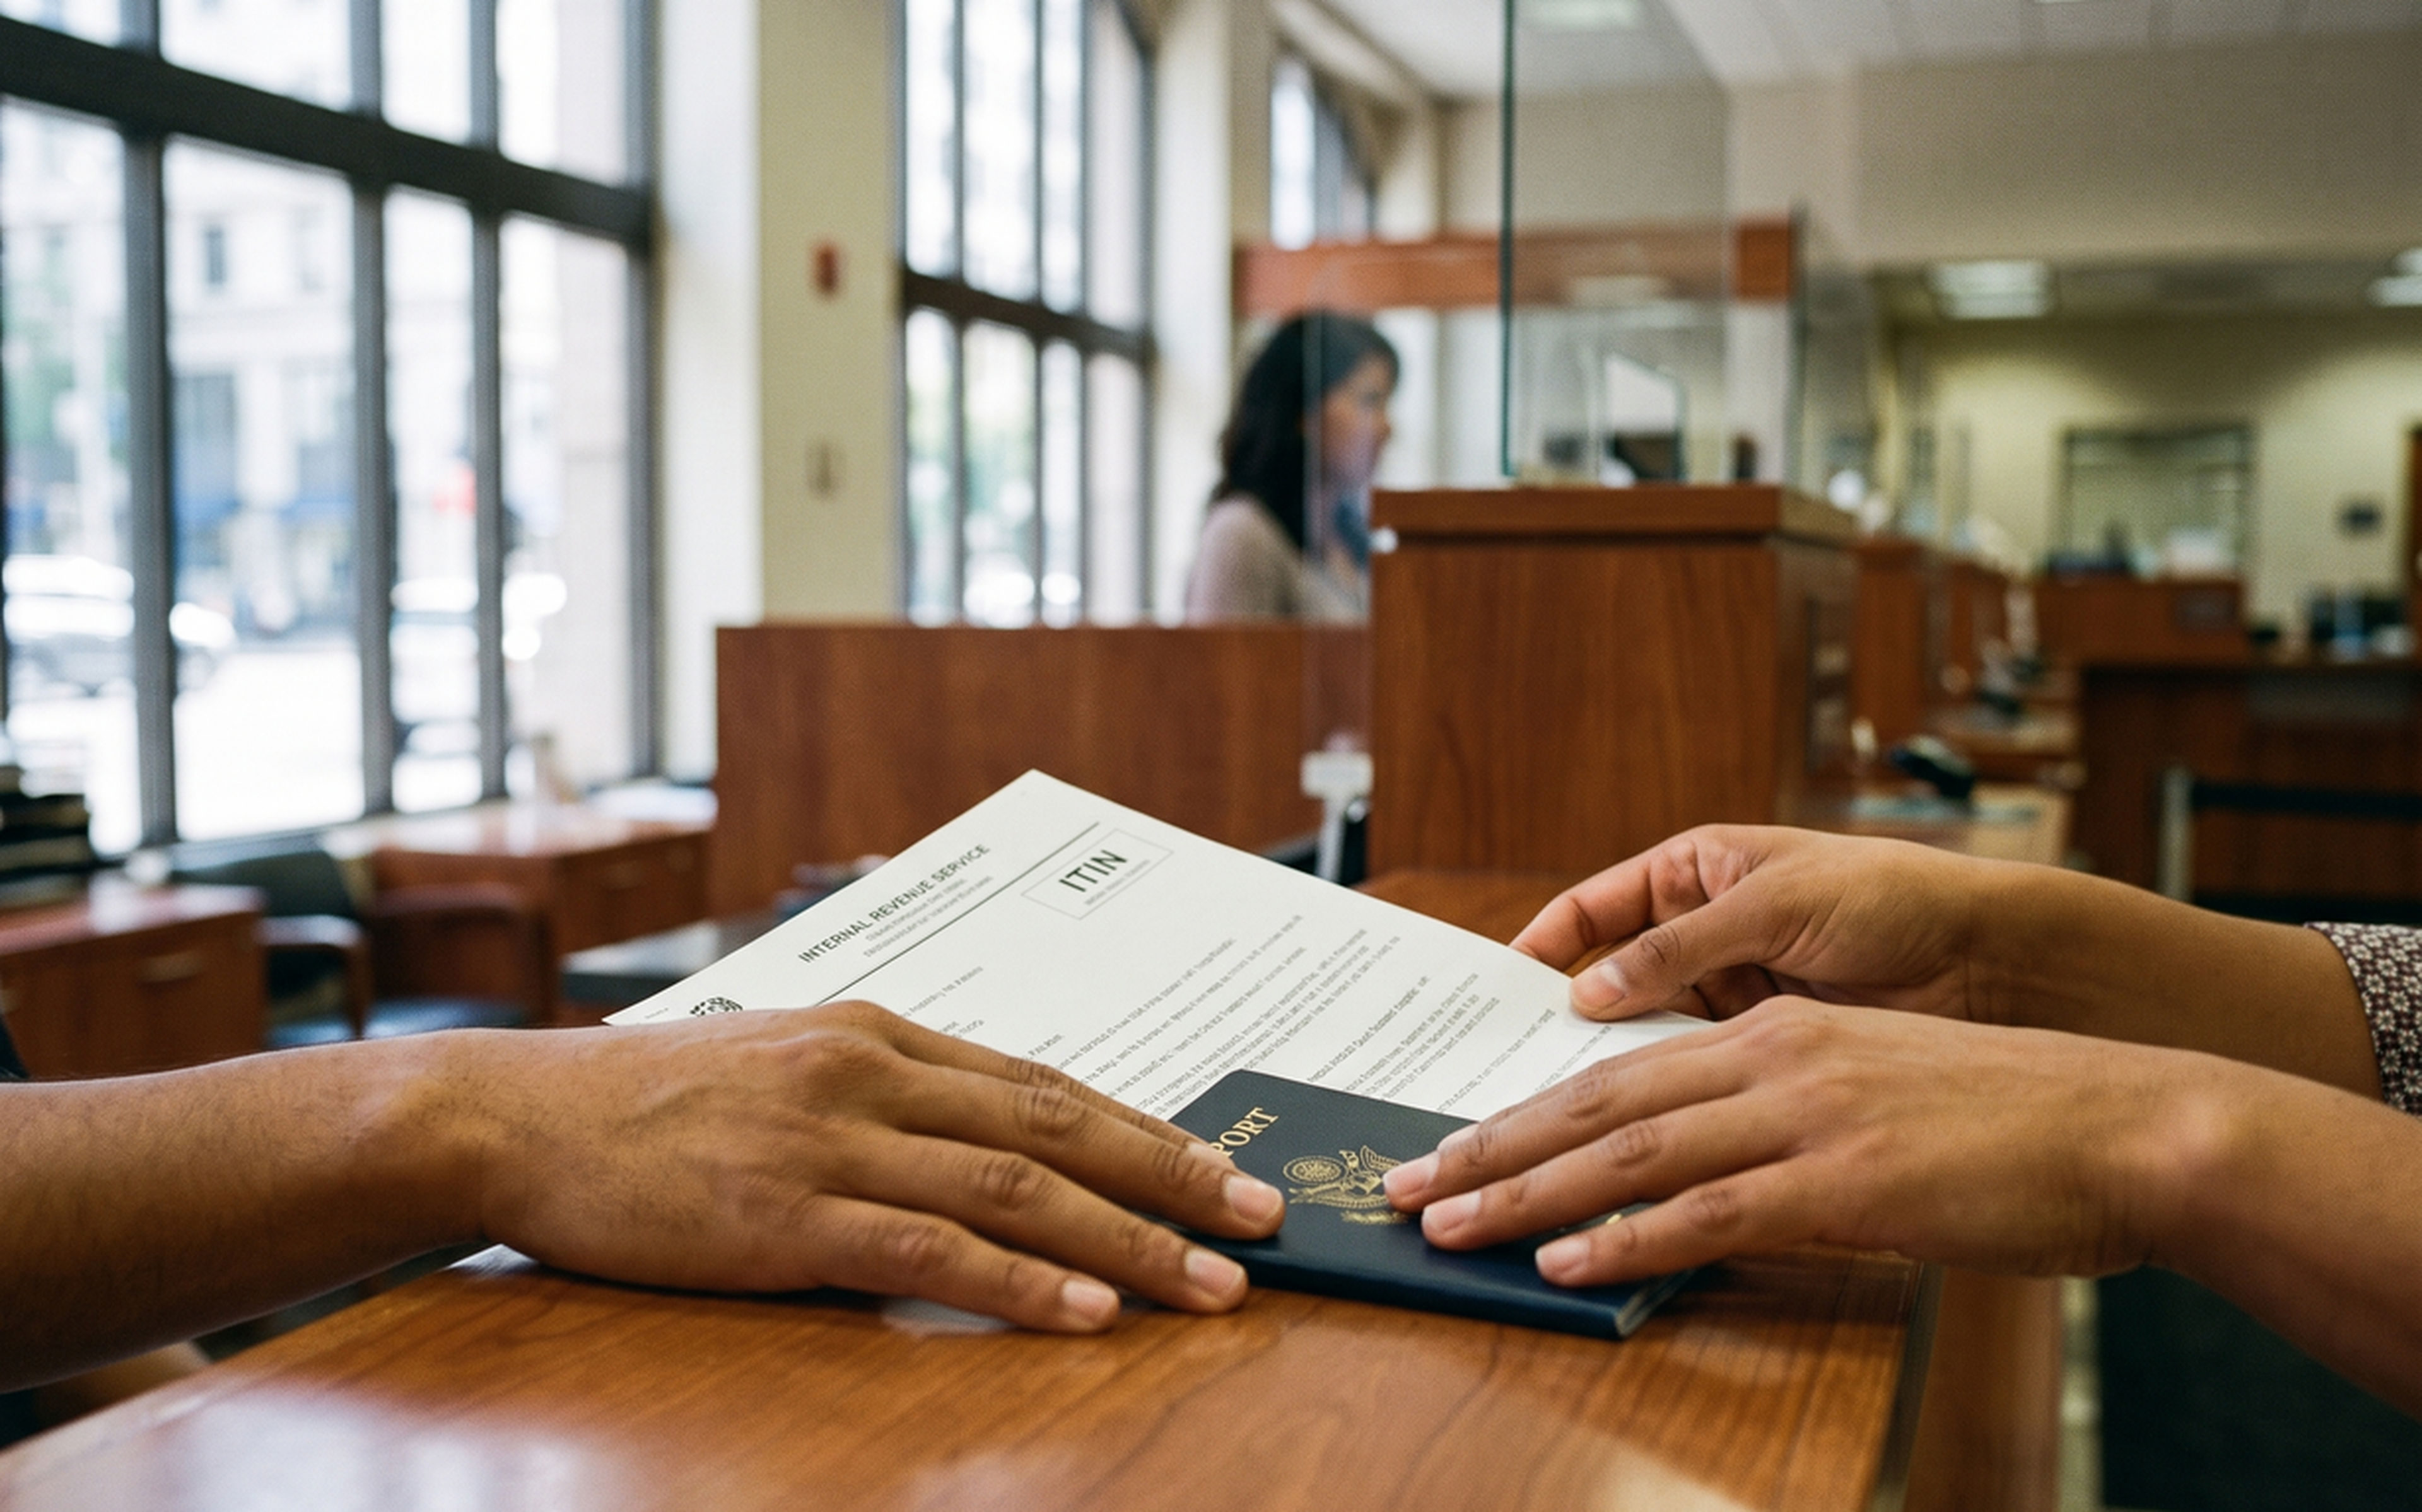
Identification: an ITIN plus a government-issued photo ID, like your passport. In some cases, a passport alone is enough.
Proof of address: a lease, a utility bill, or a piece of mail addressed to you. This trips people up more often than the ID does.
An opening deposit: often small, sometimes as little as $25. Some banks don’t ask for one at all.
A U.S. phone number: not always required, but it can speed up verification and account alerts.
Don’t have an ITIN yet? Our guide on how to get an ITIN number walks you through the application, and what an ITIN is and who needs one covers the basics.
Call the branch before you go. Requirements aren’t always clear on a bank’s website, and a five-minute call can save you a wasted trip.
Once money is moving through your new account, sending it home is the natural next step. Ria lets you transfer straight from your bank account to family abroad.

Which banks and credit unions to consider
Several major national banks are commonly reported to accept an ITIN in place of an SSN, including:
Chase
Bank of America
Wells Fargo
Capital One
PNC
US Bank
There’s a catch: most banks’ online account-opening systems aren’t set up for applications without an SSN, so plan on opening the account in person at a branch. Requirements can also vary by location, so confirm with your local branch first.
We’ve put together a closer look at some of the best U.S. banks for migrants if you want to compare a few options.
It’s also worth looking beyond the big national names. Community banks, credit unions, and CDFIs that serve immigrant communities tend to be more flexible about documentation, and many offer bilingual service. The Federal Deposit Insurance Corporation (FDIC) GetBanked page points to its BankFind tool, which can help you locate an FDIC-insured bank near you.
Step by step
Call ahead to confirm the branch’s document requirements for an ITIN-based account.
Bring your ITIN (or ITIN confirmation letter), a photo ID, proof of address, and your opening deposit.
Decide between checking and savings (more on that below). Many people open both.
Complete the application in person or online, depending on what the bank allows for your situation.
Set up online and mobile banking and your debit card right away so you’re not relying on paper statements.

Why applications actually get rejected
Most rejections come down to your banking history, not your immigration status:
More than 90% of banks check a screening service called ChexSystems before approving a new account.
ChexSystems tracks things like unpaid overdrafts, forced account closures, and suspected fraud.
Negative items typically stay on your ChexSystems record for five years.
If you’re denied because of ChexSystems, you have rights:
The bank has to tell you which screening company’s report it used to turn you down.
You’re entitled to a free copy of your ChexSystems report within 60 days of the denial.
You can also get a free report once every 12 months, whether or not you’ve been denied.
The Consumer Financial Protection Bureau (CFPB) has a guide on being denied a bank account that explains your rights and how to dispute an error. Disputes are typically investigated within 30 days.
If you have no U.S. banking history at all, ChexSystems usually has nothing negative on file for you. In that case, a rejection is more likely to come from a missing document, which is why it pays to confirm requirements ahead of time. If you’re turned down, ask the branch what triggered it before assuming the worst.
Checking vs. savings: Which to open first
A checking account is built for everyday use. It’s where your paycheck lands, where your rent and bills get paid from, and it usually comes with a debit card for day-to-day spending. Most checking accounts let you withdraw money anytime with no limit on transactions.
A savings account works differently. It’s designed to hold money you’re not touching regularly, and in exchange, it typically earns a small amount of interest, which checking accounts almost never do.
Most people open a checking account first, since it’s what you’ll use for everyday spending, direct deposit, and paying bills.
A savings account is worth adding once your checking account is set up. Even a small amount set aside monthly starts building a financial cushion. Having both accounts at the same bank is usually simpler to manage than splitting them across institutions: you can typically move money between them instantly, see both balances in one app, and avoid paying two separate sets of account fees.
A common approach once both are open: direct deposit goes into checking, and a fixed amount moves into savings automatically each payday, so building a cushion doesn’t depend on remembering to do it.

What this unlocks next
Once your account is open, a few things tend to follow:
You can set up direct deposit for a paycheck once you have a work permit.
You can start building U.S. credit history, which most lenders and even some landlords will eventually ask about.
You can send money home from a U.S. bank account instead of relying only on cash.
Frequently asked questions
Do I need a Social Security number to open a bank account?
Not at many banks. Many banks and credit unions accept an ITIN instead, especially when you open the account in person at a branch. If you’re not sure which number applies to you, see our guide on ITIN vs. SSN.
Can I open an account before I have my ITIN?
Some banks will accept a valid passport alone, without an ITIN or SSN, though policies vary a lot by institution and sometimes by branch. If your ITIN application is still pending, it’s worth calling ahead to ask.
What if I'm denied even with an ITIN?
Ask the branch what triggered the denial. A ChexSystems flag and a missing document are fixed very differently. If it’s ChexSystems, request your free report and check it for errors. If it’s a documentation gap, a community bank, credit union, or CDFI serving immigrant communities is often a more flexible next stop than another large national bank.
Do banks report your immigration status to anyone?
Opening a bank account is a financial transaction, not an immigration process. For a routine account, the bank’s checks focus on your identity, your address, and your banking history. This isn’t legal advice, though. If you have specific concerns about your situation, talk to an immigration attorney.
Can undocumented immigrants open a bank account?
Often, yes. The IRS issues ITINs to people who need a U.S. taxpayer ID but can’t get a Social Security number, and many banks that accept ITINs don’t ask for proof of a particular immigration status. Requirements still vary by bank, so confirming with your branch is the safest step.
Send money with Ria
Once your account is set up, sending money home gets a lot easier. Ria lets you send fast, cashless transfers straight from your bank account. Start your transfer today.

About the author
Gabriela Solis
Gabriela Solis is Ria's Senior Content Writer. Located in Querétaro, México, she focuses on telling stories that show the myriad human faces of remittances.
Related posts

Every Mexican consulate location in the US
Find every Mexican consulate in the U.S. by state, what each one can do for you, and how to book a free appointment through MiConsulado.

How to get a work permit in the US: Your EAD guide
There's no single US work permit. Here's who qualifies for an Employment Authorization Document (EAD), how to file Form I-765, what it costs, and the 2025 change to renewals.

Why Migrants Send Money: The Emotional Side of Remittances
Sending money home is about more than financial support. Explore the pride, love, responsibility and pressure behind remittances and what they mean for migrants.

How to Build Credit in the US as an Immigrant
Landlords, lenders, and even phone carriers check your credit, and having none can feel like having bad credit. Here's how to build a US credit file from zero, safely.