

How to Build Credit in the US as an Immigrant

If you’ve been turned down for an apartment, a car loan, or even a phone plan because you have “no credit,” it can be frustrating.
Having no credit simply means lenders don’t have enough information to see how you handle borrowed money, so they may be hesitant to approve you.
The good news is that building credit from scratch is fairly straightforward. Here’s how to get started.
Why Credit Matters
A thin or nonexistent credit file can cost you money and options in places you might not expect.
Many landlords pull a credit report before approving a lease application.
Auto lenders price your interest rate off your credit file, so no file often means a higher rate or a cosigner requirement.
Phone and utility providers often ask for a deposit specifically because they have no history to judge you on.
Some employers run a credit-based background check as part of hiring.
A stronger file now can mean better rates on insurance and larger loans later, once you need a mortgage.
Building credit early saves you these deposits and rejections down the line.
Sending money to family back home while you get your US finances in order? Ria makes that part simple. No US bank account required, fees shown up front, and fast transfers to family abroad.
What You’ll Need Before You Apply
Most credit-building products ask for the same basics: proof of identity, a US address, and either a Social Security Number (SSN) or an Individual Taxpayer Identification Number (ITIN).
If you’re eligible for an SSN, that’s the identifier most lenders expect by default.
If you’re not, an ITIN works for most secured cards and credit-builder loans. It’s a tax-processing number issued by the Internal Revenue Service (IRS) to people who aren’t eligible for an SSN. What Is an ITIN, and Do You Need One? covers who needs one, and How to Get an ITIN Number — Step by Step walks through the application.
Proof of address, like a lease or a utility bill, and proof of income round out most applications.
Some banks will open an account with just an ITIN. If you haven’t set one up yet, here’s how to open a US bank account without an SSN, since a checking account makes it easier to fund a secured card or make credit-builder payments.

Step 1: Get a Secured Credit Card
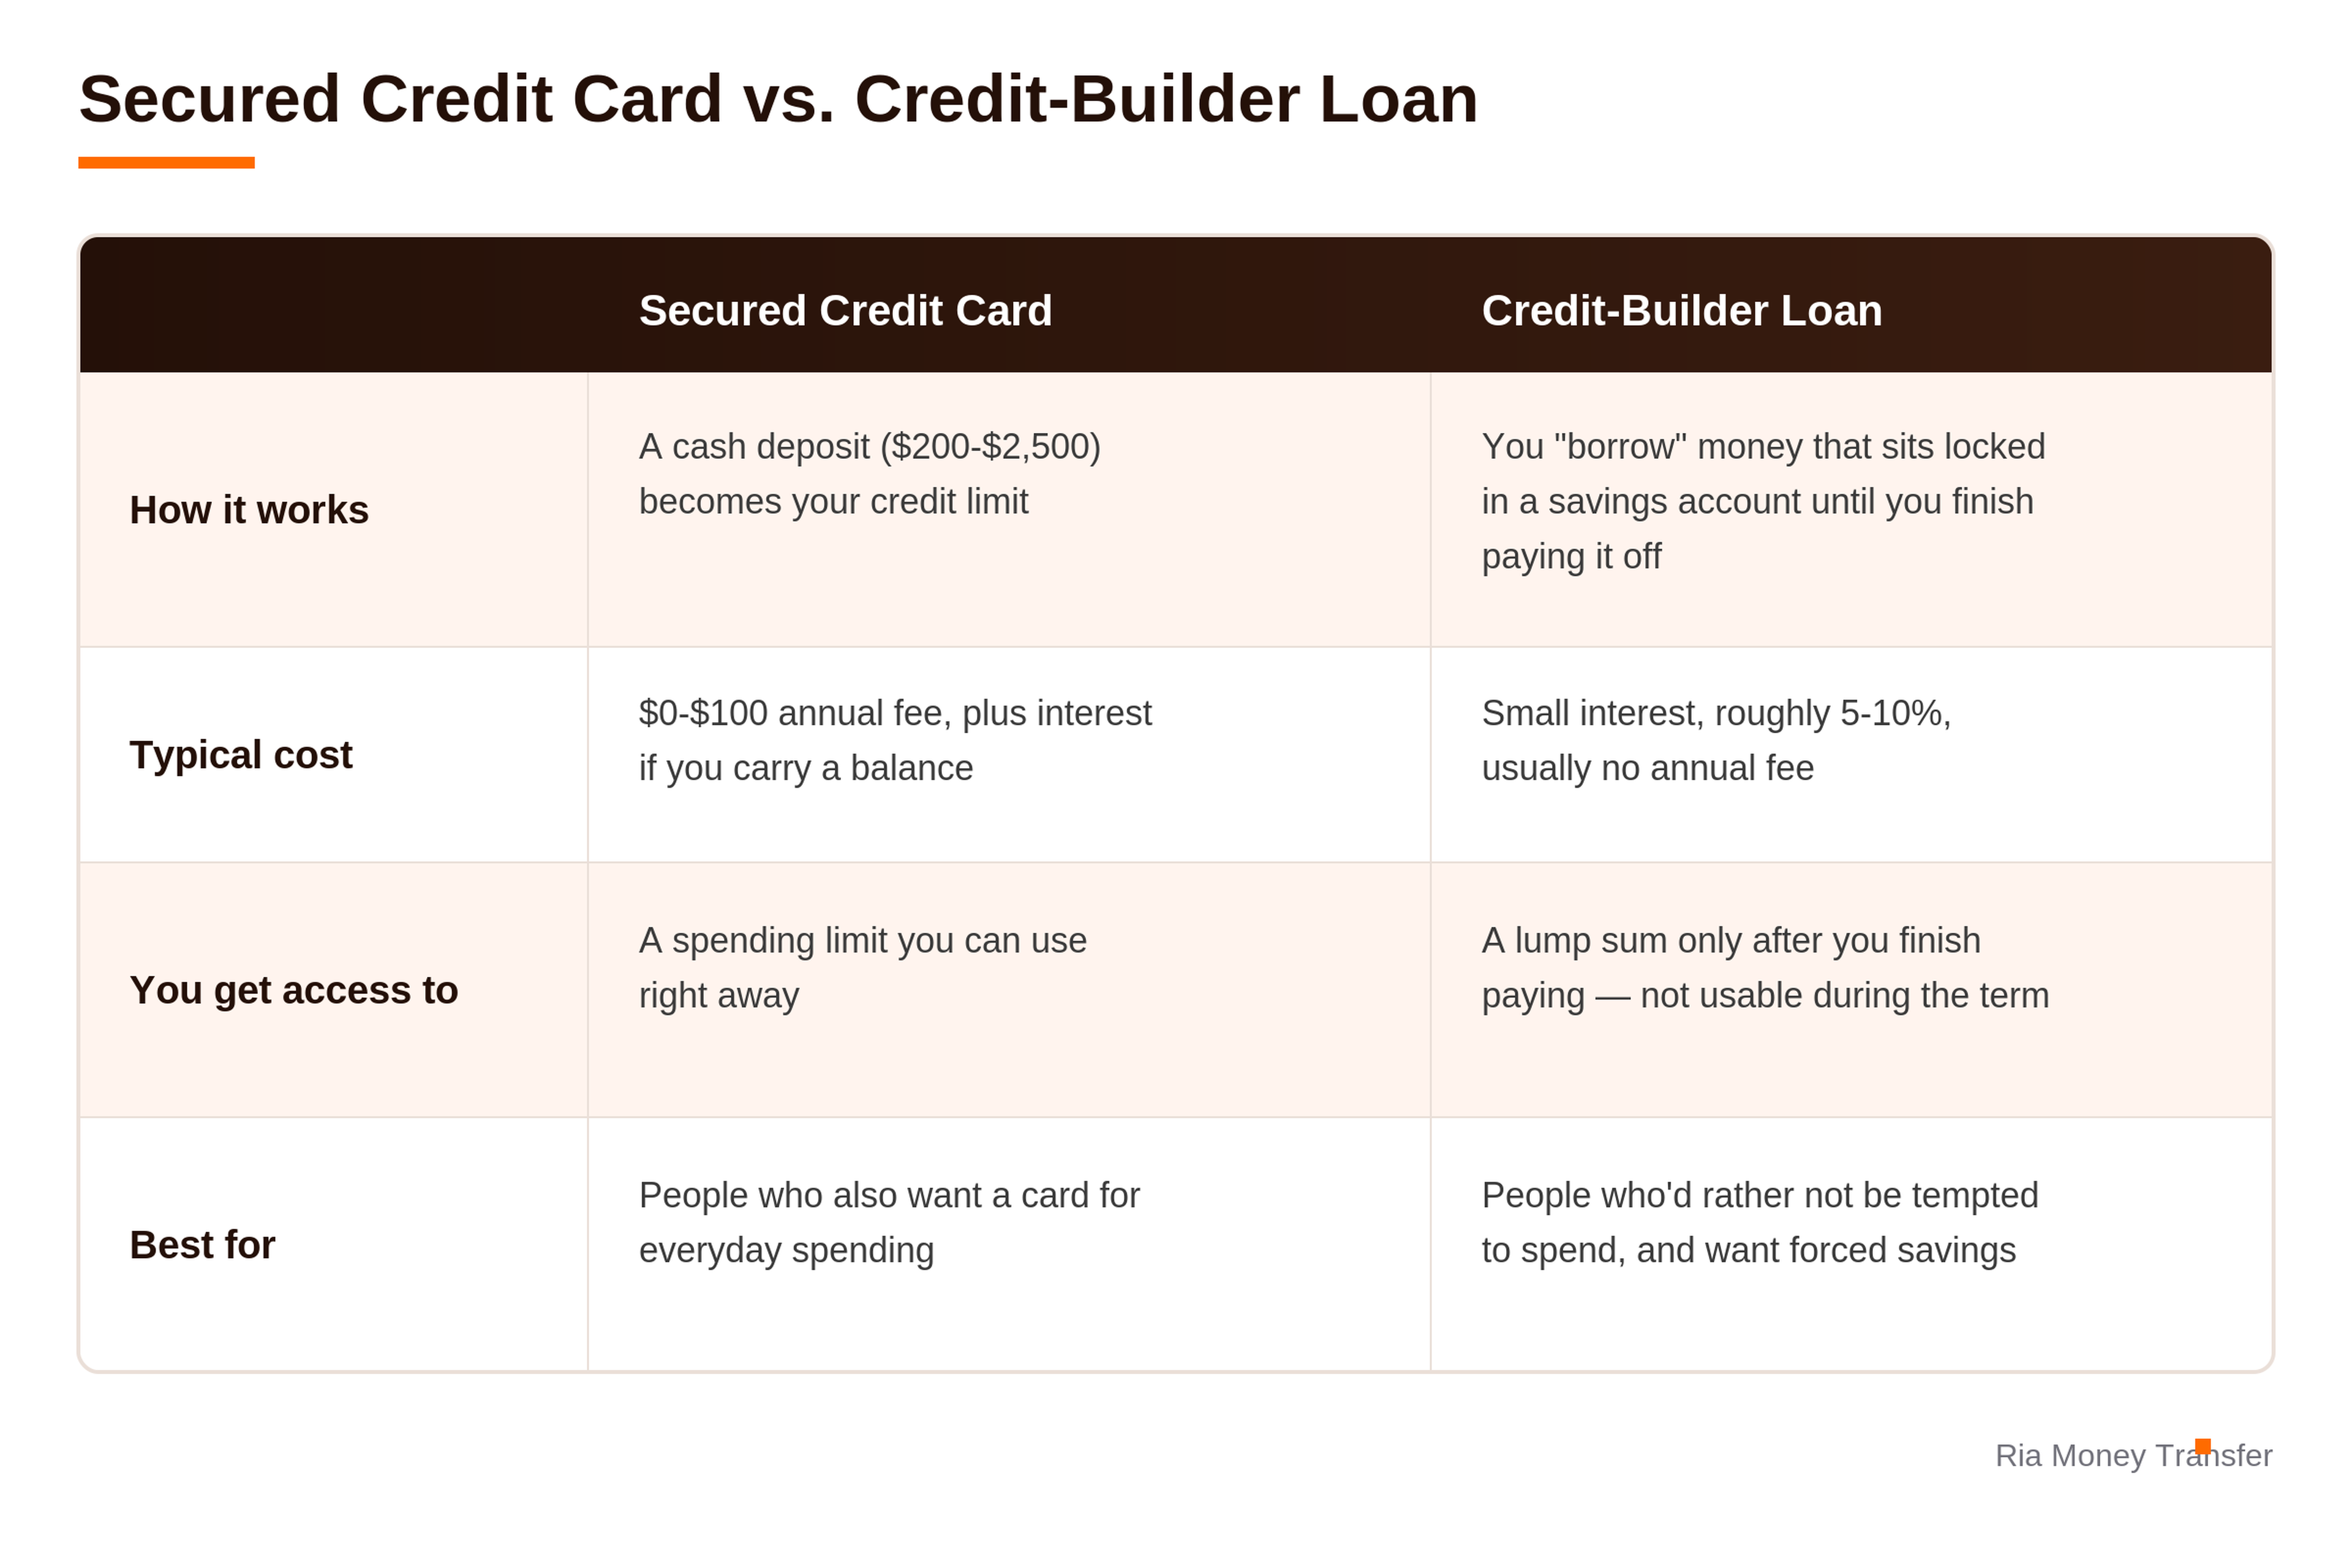
A secured credit card is usually one of the quickest realistic starting points when you have zero credit history, because approval is based on a deposit rather than a credit check.
You put down a cash deposit, commonly somewhere between $200 and $2,500, and that amount becomes your credit limit.
You use the card like a normal one, and the issuer reports your payment activity to the credit bureaus every month, which is what actually builds your file over time.
Look for a secured card with no or a low annual fee. Check whether the issuer has a path to graduate you to a regular unsecured card, refunding your deposit, after a run of on-time payments. Many do.
Step 2: Consider Becoming an Authorized User
If a trusted family member has a US credit card in good standing, ask whether you can be added as an authorized user.
Their card’s payment history can start showing up on your credit report too, sometimes speeding things up considerably, but this only helps if their account is genuinely well managed, since their late payments could show up on your file as well.
It’s a favor worth asking for, not one to force if it isn’t naturally available to you.

Step 3: Look Into a Credit-Builder Loan
Some credit unions and community banks offer credit-builder loans designed exactly for this situation.
You “borrow” a set amount, often $300 to $5,000, but instead of receiving the cash, it sits in a locked savings account while you make fixed monthly payments over 12 to 24 months.
Once you’ve paid it off, you get the money. The cost is usually just modest interest, without the annual fees a secured card might carry, and your payment history gets reported the same way.

The Habits That Actually Move Your Score
Pay on time, every time. Payment history is the single biggest factor in most scoring models, worth roughly 35% of a FICO Score.
Keep your balance well below your limit. Using less than 30% of your available credit tends to help, and lower is generally better.
Don’t close your oldest account once you have other options. Length of credit history matters too.
Avoid applying for several new cards or loans in a short window, since each application can ding your score slightly.
How Long It Realistically Takes
There’s no fixed timeline, but a rough pattern holds for most people who stay consistent:
First reporting cycle or two: your file starts to exist, but there isn’t enough history yet to generate a score.
Around 6 months: many people with a secured card or credit-builder loan and on-time payments reach a scorable file.
1 to 2 years: consistent on-time payments and low utilization typically move you from a thin file into fair or good territory.
Patience and consistency matter more here than any single trick.

A Caution on Credit Repair Scams
Immigrants are a specific, documented target for credit and debt scams.
The Federal Trade Commission’s (FTC) guidance on scams against immigrants covers common tactics, and federal regulators have taken action against companies that specifically preyed on immigrants with threats tied to their status.
A legitimate credit-building company won’t guarantee a specific score increase, ask you to create a new credit identity, or pressure you to sign a contract you don’t fully understand.
If something feels like it’s using your immigration status as leverage, treat that as a red flag on its own.
Check Your Credit for Free
You’re entitled to a free credit report from each of the three major bureaus every week, through the one federally authorized source: AnnualCreditReport.com.
The FTC made this weekly access permanent in 2023, on top of the free annual report the law has guaranteed for years.
Plenty of other sites advertise “free” credit reports or scores with strings attached. This is the one that’s actually free by law, and it won’t show you a credit score, only the report itself.

FAQs
Does my ITIN affect my credit score?
An ITIN itself isn’t a credit factor. It’s just a way to apply for credit products without an SSN. Your score is built from your payment history and account activity, the same as anyone else’s, once you have accounts reporting to the bureaus.
Can I check my credit for free?
Yes. All three bureaus offer free weekly reports through AnnualCreditReport.com, the only site authorized to provide this for free.
Does having no credit history hurt me the way bad credit does?
It can produce similar rejections in the short term, since lenders and landlords often can’t distinguish ‘no information’ from risk at a glance. The difference is that no credit history is quicker to fix. Bad credit takes longer to repair, since negative marks typically stay on a report for years.
Can my immigration status affect my ability to get credit?
Most credit products are based on your ability to provide identification, an ITIN or an SSN, and show income, not your immigration status directly.
What counts as a good credit score once I have one?
For the FICO Score model most lenders use, 670 to 739 is considered good, 740 to 799 very good, and 800 or above exceptional, on a scale that runs from 300 to 850. You don’t need a perfect score to qualify for solid rates. Crossing into the high 600s already opens up most mainstream products.
Will carrying a small balance help my score more than paying it off?
No, that’s a common myth. Paying your statement in full each month avoids interest and still reports as on time, which is what actually helps your score. What matters is that you’re using the card at all, not that you deliberately carry debt.
Send Money With Ria
Once your finances are on solid footing in the US, sending money home is the easy part. Ria lets you send fast, cashless transfers to family abroad. Start your transfer today.
About the author
Gabriela Solis
Gabriela Solis is Ria's Senior Content Writer. Located in Querétaro, México, she focuses on telling stories that show the myriad human faces of remittances.
Related posts
How to Open a US Bank Account Without an SSN
Here's what you actually need to open a US bank account as an immigrant, and how to avoid the most common reasons applications get turned down.
ITIN vs SSN: What's the Difference and Which Do You Need?
An ITIN and an SSN aren't interchangeable, even though both let you file US taxes. Here's what separates them and which one applies to you.
What Is an ITIN and Do You Need One?
An ITIN lets you file US taxes and open many bank accounts without a Social Security number. Here's who needs one, what it does, and what it costs.
Moving to the US from Colombia: Your Financial Checklist
Everything to sort out in your first months in the US if you're coming from Colombia: ITIN, bank account, work permit, consulate, and how to send money home.